Blog
Auction Loans With No Interior Photos: What Lenders Need
By Jason Taken · Principal
7 minute read
Buying an auction flip without interior photos? Build a review file, identify funding conditions, and confirm the no-access path with Jaken Finance Group.
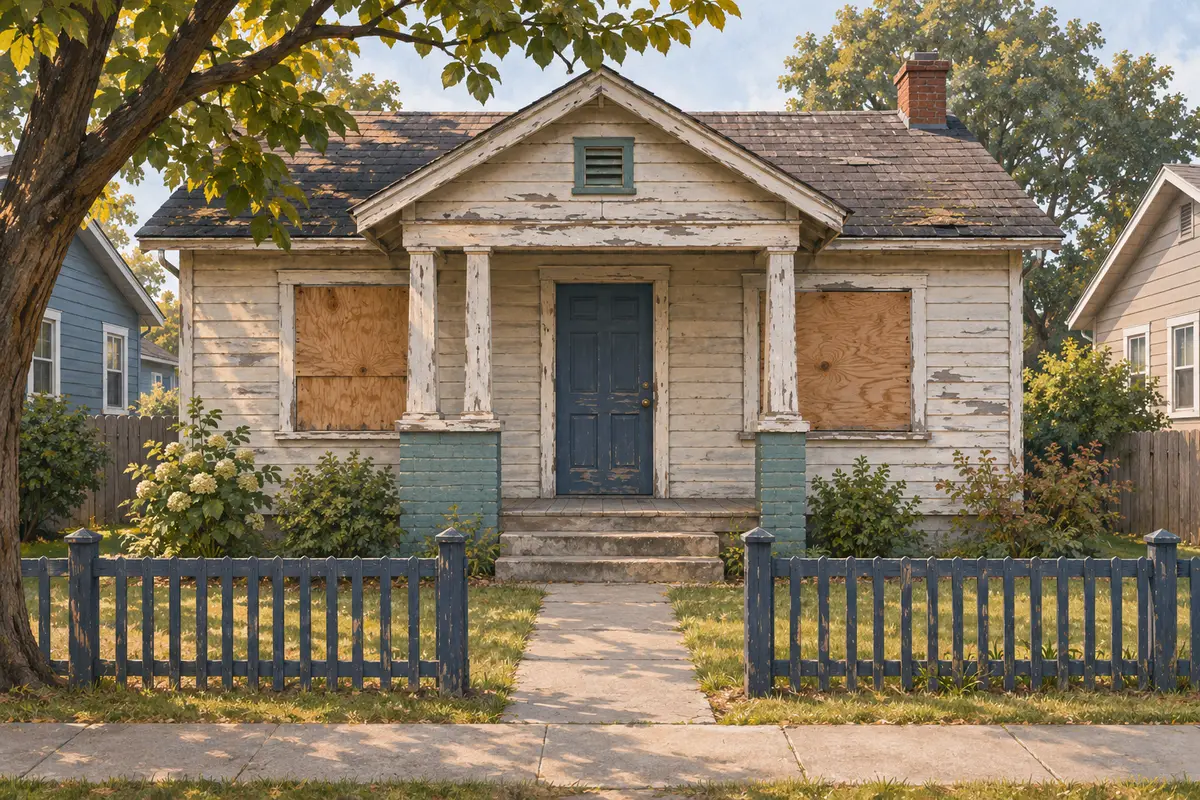
The auction listing has one exterior photo. The windows are boarded, the property is occupied, and the last interior listing is several years old. You need to know whether a lender can fund the purchase before you commit a deposit.
An auction loan without interior access starts with an evidence review. A buyer who cannot personally tour a house may still have a recent room-by-room photo set. A house with no usable interior photos presents a larger information gap. Those situations should not receive the same financing assumption.
Jaken Finance Group’s photo-funded fix-and-flip program serves listed metros and qualified files. Its published process uses photos and sold comparable sales. Ask the team to review the actual evidence before treating a no-access property as eligible. Submit the auction property for a financing review with the missing information clearly identified.
Separate the three access questions
Write down whose access is unavailable and when. “No access” can describe three different constraints:
| Question | What you need to establish |
|---|---|
| Can the buyer inspect before bidding? | What the seller permits before the bid becomes binding |
| Can the lender obtain its required evidence before funding? | Whether the proposed valuation and condition review can be completed |
| Can contractors and draw inspectors enter after acquisition? | When lawful possession and the rehab schedule can begin |
A seller may refuse your walkthrough while supplying useful interior photos. Another seller may supply nothing beyond a street image. A lender may accept alternative evidence for an initial decision while requiring additional documents before disbursement.
Keep these questions separate in every email. “Can you lend without my visiting?” is less useful than “Can you fund acquisition with the attached evidence, while interior entry remains unavailable?” The second question exposes the condition that could stop the transaction.
Start with the sale’s financing restrictions
The lender’s willingness to consider a property and the seller’s willingness to accept that financing are separate decisions. Auction.com says some REO and private-seller transactions may accept non-contingent financing, subject to seller approval. Its FAQ also warns that financing dependent on inspection or appraisal of the subject property may be unacceptable. Check the specific listing and contract. Auction.com financing FAQ
Send the sale documents with the photos. Include the deposit deadline, balance deadline, accepted payment method, and any financing restrictions. Ask whether the proposed loan can actually produce accepted payment under those terms.
If payment is due before the lender can finish its conditions, a possible loan structure does not solve the auction purchase. The cash-only auction funding guide explains how to compare seller acceptance with lender readiness.
Build a photo record that shows what is missing
Make a simple image index. For each image, record its source, approximate capture date if known, room or exterior view, and limitations. Preserve the original file or listing record when you can.
Use these categories:
- Current exterior observations made from a permitted location.
- Interior images supplied by the seller, listing broker, or another authorized source.
- Historical listing photos, clearly identified as historical.
- Reports or disclosures that the seller makes available.
- Areas with no reliable visual evidence.
Do not label an old kitchen photo “current condition.” A clean room in a previous listing establishes what was visible then. It does not establish today’s roof performance, plumbing condition, or occupancy.
Flag contradictions directly. If an assessor record shows two bathrooms but a historical listing shows one, list the discrepancy. If a photo shows a finished basement but permitted area is uncertain, keep that space separate in the valuation discussion. The lender can then identify what must be verified.
For the broader photo checklist, use the existing fix-and-flip loan without property access guide. For a property with no interior evidence, make the missing-room list as prominent as the pictures you do have.
Give each unknown a financing consequence
An unsupported assumption is most useful when connected to the decision it could change. Build a short table like this:
| Unknown | Current working assumption | Consequence if wrong |
|---|---|---|
| Interior water damage | Repair allowance remains provisional | Scope and cash requirement could rise |
| Electrical service | Replacement priced as an alternative | Contractor estimate and permits may change |
| Legal living area | Only verified area used for value | Finished-value estimate may fall |
| Occupancy and access date | Possession remains unconfirmed | Carry begins before rehab can start |
| Insurance availability | Quote requested for actual condition | Acquisition funding may need different coverage |
Avoid presenting the table as a completed inspection. Its purpose is to show what your analysis depends on. Ask which unknowns the lender can accept with a documented allowance and which require resolution before funding.
A large contingency cannot fix every gap. If the property might require structural work that the proposed program will not finance, the issue is eligibility as well as cost. Get that question answered before increasing your bid.
Support value separately from condition
After-repair value, or ARV, estimates the property after a defined renovation. As-is value addresses its present state. Your file should explain both concepts without treating an attractive resale comp as proof of current condition.
Use sold properties that resemble the subject’s verified size, layout, location, and intended finish. Explain why a nearby sale fits. If the subject’s interior layout remains unknown, show the uncertainty rather than assuming the most valuable configuration.
Prepare a lower-value case tied to specific facts. For example, remove an unverified basement bedroom from your resale assumptions and recalculate the project. The auction rehab estimate guide shows how to pair that value case with repair scenarios.
Jaken Finance Group’s general appraisal policy is:
No appraisal required on select bridge and fix-and-flip programs for experienced sponsors with documented ARV comps. Standard programs use third-party valuation.
That policy requires a file-specific decision. It does not establish that an exterior image is sufficient or that every auction purchase qualifies. Agency loans also have defined valuation alternatives; “conventional always requires a walkthrough” is too broad. Fannie Mae describes several methods, each with eligibility requirements. Those agency rules do not determine Jaken Finance Group’s private lending decision. Fannie Mae property valuation FAQs
Request a decision in stages
Ask the loan officer to distinguish the following responses:
- Initial review: Is the address, property type, intended use, and evidence package worth further underwriting?
- Proposed terms: What loan amount and structure could apply, and what assumptions support them?
- Acquisition conditions: What must be completed before money can be disbursed for this sale?
- Rehab conditions: What controls later draws, including access, inspections, and approved scope?
The answer “we can review it” belongs to the first stage. It should not be recorded in your bid worksheet as a funded commitment.
Jaken Finance Group’s published fix-and-flip closing range is 7–10 business days. Closing times begin after borrower conditions are satisfied. Compare the actual remaining conditions with the sale deadline; a published range does not reserve an auction closing slot.
Example: how two missing facts change the bid decision
Consider a hypothetical auction ranch with a $140,000 proposed bid and a $55,000 provisional repair budget. The buyer has exterior photos and a four-year-old interior listing. The contractor priced a systems replacement alternative, but no one has verified the basement or current occupancy.
The useful lender request is not “Please approve $195,000 of cost.” It is:
“Please review the attached evidence. The interior photos are historical. We have no current basement images, and possession timing is unknown. Can acquisition funding proceed under these facts? Which conditions remain, what rehab reserve would be held back, and what additional evidence could change the amount?”
Suppose the response requires a condition report before funding. If the seller will not allow the required access, that financing path does not fit the sale. If an alternative review is acceptable, obtain its conditions in writing and revise the cash plan. Neither response makes the missing evidence disappear.
Submit one complete pre-bid packet
Include a one-page summary with the property address, sale type, maximum contemplated bid, payment dates, and requested structure. Attach the sale documents, indexed evidence, repair scenarios, sold comps, occupancy notes, and entity information. State available cash after obligations to other projects.
Identify your experience and contractor support accurately. Explain whether the intended exit is resale or a rental refinance, and what would happen if repairs cost more or possession takes longer. A rental exit requires its own underwriting later.
Use the fix-and-flip submission form and ask for an address-specific no-access review. Before bidding, you need an answer about the evidence and acquisition conditions on this property, a payment plan the seller accepts, and enough cash to carry the uncertainty that remains.