Updated
Cost segregation identifies property components that belong in shorter depreciation periods. Bonus depreciation determines how quickly eligible costs may be deducted. Your tax circumstances determine whether those deductions reduce this year’s tax bill. These are three separate decisions, and an attractive result at one stage does not settle the others.
For an investment-property owner, the practical objective is to assemble reliable costs and dates, understand the possible change in deduction timing, and compare that change with the study’s fee and the expected ownership period. A building purchase is not automatically a building-sized write-off. A large projected deduction is not automatically cash available for another down payment.
This guide explains the federal framework using primary IRS sources checked November 3, 2026. It is educational information, not an individual tax opinion. Start with the free bonus depreciation and cost segregation field guide (PDF), then use the date organizer below to prepare for your CPA conversation.
What changed in bonus depreciation?
The One Big Beautiful Bill Act restored a 100% additional first-year depreciation deduction for qualifying property acquired and placed in service after January 19, 2025. IRS Notice 2026-11 explains the interim framework, including how existing regulations apply with modified dates and percentages. The word qualifying matters as much as the percentage.
A property acquired under earlier rules can remain subject to a different bonus percentage even if work finishes later. Written binding contracts, certain used-property acquisitions, self-constructed property and components can require additional analysis. Asking only when a deed recorded is an incomplete eligibility check. Keep the signed purchase agreement, amendments, closing statement and improvement contracts together.
The restoration also does not eliminate elections or every interaction with other provisions. Notice 2026-11 describes a reduced-percentage election for the first tax year ending after January 19, 2025. Section 179 is a different provision with separate requirements and limitations. Your preparer should decide which rules apply instead of adding multiple deductions to the same dollar of cost.
Use the IRS business provisions overview to locate current implementation guidance, and check the source relevant to the return being prepared. A permanent rule means the statute removed the scheduled phase-down for the qualifying category; it does not mean every property or taxpayer qualifies permanently without further review.
What does a cost segregation study change?
A study analyzes the property’s costs and components. Some costs that appear in a building acquisition or construction budget may belong to personal property or land improvements rather than the long-lived structure. Correct classification can move deductions earlier, with eligible shorter-life property potentially receiving bonus depreciation under the applicable rules.
IRS Publication 946 describes the depreciation framework. Residential rental real property generally uses a 27.5-year recovery period under the general depreciation system; nonresidential real property generally uses 39 years. Specific assets, methods, elections and required alternative depreciation treatment can change the analysis. The name an owner gives a rental is not a substitute for classification.
A component’s physical appearance does not settle its tax treatment. Carpeting, equipment, site work and specialized systems may present different questions from structural elements. Permanence, function, use and the relevant legal classification matter. A generic list of “everything inside the building” is not a defensible cost allocation.
The IRS Cost Segregation Audit Technique Guide discusses how examiners evaluate studies, methods and documentation. It is useful for understanding study quality, but the guide itself is not an official pronouncement of law. Neither the existence of that guide nor a provider’s use of similar language means the IRS approved a particular study.
Establish the cost before estimating the deduction
Start with acquisition records and reconcile them to the property you actually own. Separate land, identify costs that belong to depreciable assets, and have the CPA classify subsequent expenditures. Financing costs, repairs, capital improvements and acquisition costs do not all receive identical treatment. A spreadsheet that calls every outgoing payment “basis” can overstate the starting amount.
Land is excluded from depreciation. Exclude it once, using a supportable allocation, rather than subtracting land from a figure that already excludes it. Where a purchase includes multiple assets, the allocation should make sense across the complete transaction. The study provider and CPA need a reconciled total, not separate estimates that add up to more than the actual cost.
Keep later improvements distinct when their dates or tax treatment differ. A building bought last year and equipment installed this year are not necessarily one asset with one acquisition date. Records should identify the expenditure, invoice, purpose, payment, completion and service date. A summary may be convenient, but its underlying evidence must remain available.
Tax basis also differs from market value and debt. An appraisal can support a lender’s collateral analysis without establishing depreciation cost. A cash-out refinance can change the loan balance without creating a new building purchase. Publication 527 explains residential rental costs and basis; use it with the CPA’s actual adjustment schedule.
Track five dates separately
The most useful timing exercise is not a single year-end deadline. It is an evidence trail showing what happened and when. A contract date, acquisition closing, rental readiness, report delivery and refinance closing answer different questions. Treating them as interchangeable is a common source of bad projections.
| Milestone | Evidence to keep | Question it helps answer |
|---|---|---|
| Contract signed | Executed agreement and amendments | Which acquisition rules and contract provisions require review? |
| Acquisition closed | Settlement statement and ownership records | When did this owner acquire the property? |
| Ready and available | Completion records, listing history and required approvals | When could the property serve its intended rental use? |
| Study delivered | Engagement and final report | When are supported allocations available for the preparer? |
| Refinance closed | Loan and appraisal documents | How did the financing change? |
A first tenant can arrive after a rental was ready and available. Conversely, advertising an unfinished or unusable property does not necessarily establish readiness. Required approvals, the property’s condition and actual availability need to be evaluated together. Keep objective records rather than selecting the most favorable date after seeing a tax estimate.
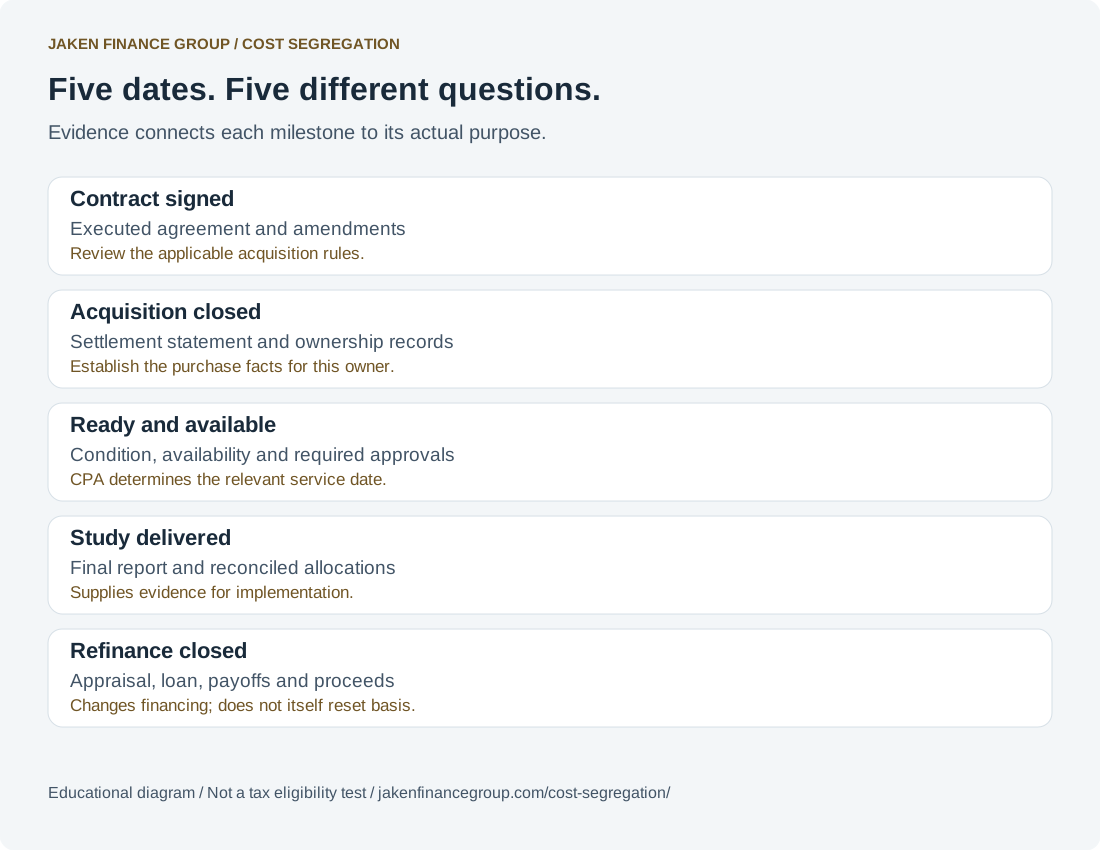
Open the full-size date and evidence infographic.
WORK THROUGH YOUR ASSUMPTIONS
Cost segregation date organizer
Record five separate milestones. Dates alone do not establish bonus eligibility; contract terms, asset facts and elections still require review.
Entries stay on this page. Nothing is submitted, saved or sent to Maven.
Worked example: a September rental opening
This illustration is deliberately simplified. An investor buys a duplex for $245,000 and makes $73,000 of capital improvements. Assume the CPA supports a $33,000 land allocation and $285,000 of depreciable cost. Assume a September 2026 service date and that a property-specific study assigns $100,000 to assets qualifying for 100% bonus depreciation.
The remaining $185,000 is assumed to be residential rental building basis using a 27.5-year recovery period. For September, the mid-month convention produces 3.5 months of depreciation in the first calendar year. Using a full year’s building depreciation would overstate the first-year amount. Actual return calculations follow the applicable tables, classifications and conventions.
| Simplified calculation | Amount |
|---|---|
| Purchase plus capital work less land | $245,000 + $73,000 − $33,000 = $285,000 |
| Assumed eligible bonus amount | $100,000 |
| Remaining building amount | $185,000 |
| First-year building deduction | $185,000 ÷ 27.5 × 3.5 ÷ 12 ≈ $1,962 |
| Total first-year depreciation | Approximately $101,962 |
| Building-only comparison | $285,000 ÷ 27.5 × 3.5 ÷ 12 ≈ $3,023 |
| Incremental first-year deduction | Approximately $98,939 |
The comparison treats every depreciable dollar as building cost without a study. An actual existing schedule may already identify some separate assets, making that baseline too simple for a real engagement. Obtain both actual schedules before calculating an incremental benefit. The $98,939 difference is a deduction difference, not a promised tax saving.
Why December changes the building calculation
Consider a second hypothetical duplex: $260,000 purchase, $55,000 capital improvements and $70,000 allocated to land. Assume $245,000 of depreciable cost, including $73,500 of eligible bonus assets and $171,500 remaining building basis. If it becomes ready and available in December, the building receives half a month’s depreciation under the assumed mid-month convention.
The building amount is about $260: $171,500 divided by 27.5, multiplied by 0.5 divided by 12. Add the assumed $73,500 bonus deduction and the total is approximately $73,760. A simplified building-only comparison on $245,000 produces about $371 for that year. These are rounded illustrations, not filing schedules or typical allocation percentages.
If readiness instead occurs in January, the deduction belongs in a different tax year. That does not mean the investor should rush unsafe work or choose an unsupported date. It means project scheduling and evidence matter. Ask the CPA to evaluate the actual facts before the final draw, rather than treating a planned completion date as a completed tax event.
A deduction must still be usable
IRS Publication 925 explains passive activity and at-risk limitations. Rental losses are generally passive unless an applicable exception or rule changes the result. A substantial depreciation deduction can therefore produce a suspended loss rather than a current reduction in tax on wages or other nonpassive income.
Active participation, material participation and real estate professional status are different concepts. They should not be used as interchangeable labels. Real estate professional status has annual service requirements, and material participation still matters in the relevant rental activities. A large study does not create those facts after the year is over.
The familiar special rental loss allowance is subject to conditions, income limits and filing-status rules. It is not a blanket permission to offset every investor’s W-2 income. Similarly, an owner who expects passive income should ask whether that income is available in the right category and year. The preparer must evaluate the complete return.
State treatment deserves its own line in the model. A federal deduction can coexist with a state adjustment, a different depreciation schedule or different limitations. This guide does not assume state conformity. Before spending a projected state tax saving, identify the specific state, taxpayer and return year, then have the preparer verify the governing rules.
Evaluate fees and the eventual sale
A study moves deductions through time; it does not necessarily add new lifetime depreciation to the same costs. Compare the timing benefit with the actual quoted fee, the ability to use deductions and the expected ownership period. There is no universal purchase-price threshold that makes a study worthwhile regardless of these factors.
Sale consequences can change the result. IRS Publication 544 explains disposition rules, including depreciation recapture. Asset categories matter: potential ordinary-income recapture on Section 1245 property and unrecaptured Section 1250 gain should not be collapsed into one assumed rate. Ask for an asset-level sale analysis when evaluating a short hold.
The right comparison is an after-tax ownership plan with and without the study, using the same purchase, operations and exit assumptions. A favorable first-year result can be useful without proving the study has a favorable lifetime result. The study economics guide explains a practical sequence for comparing those questions.
Use a calculator as a conversation starter
A preliminary calculator can help an owner decide whether to investigate. It cannot inspect the property, reconcile every cost, review every election or determine how a loss affects the owner’s complete return. Entering a purchase price and choosing a tax rate is not equivalent to ordering a supported engineering analysis.
Before relying on an estimate, ask which inputs exclude land, whether the tool accounts for acquisition as well as service dates, and how its baseline schedule is constructed. Ask whether it assumes the entire deduction is usable immediately. A tool that shows a large number may be answering a narrower question than the investor believes.
Coordinate the study with the investment file
Keep financing analysis independent. Rent, operating expenses, reserves and scheduled debt payments determine whether the property can support its borrowing. A projected deduction does not increase rent or reduce the mortgage installment. Use the DSCR calculator for coverage and the BRRRR calculator for project capital assumptions.
Give the CPA and provider one organized file containing acquisition documents, a land allocation to review, improvement records, service-date evidence and existing depreciation schedules. Ask who will reconcile the report to the return, who will answer follow-up questions and which deliverables are included in the fee. A clear handoff is more useful than a deadline promise without complete records.
If the property was already reported in prior years, use the existing-property guide before deciding how to implement a study. If the operation is a short-term rental, use the STR guide to separate its additional factual questions. Keep each decision connected to the evidence that supports it.