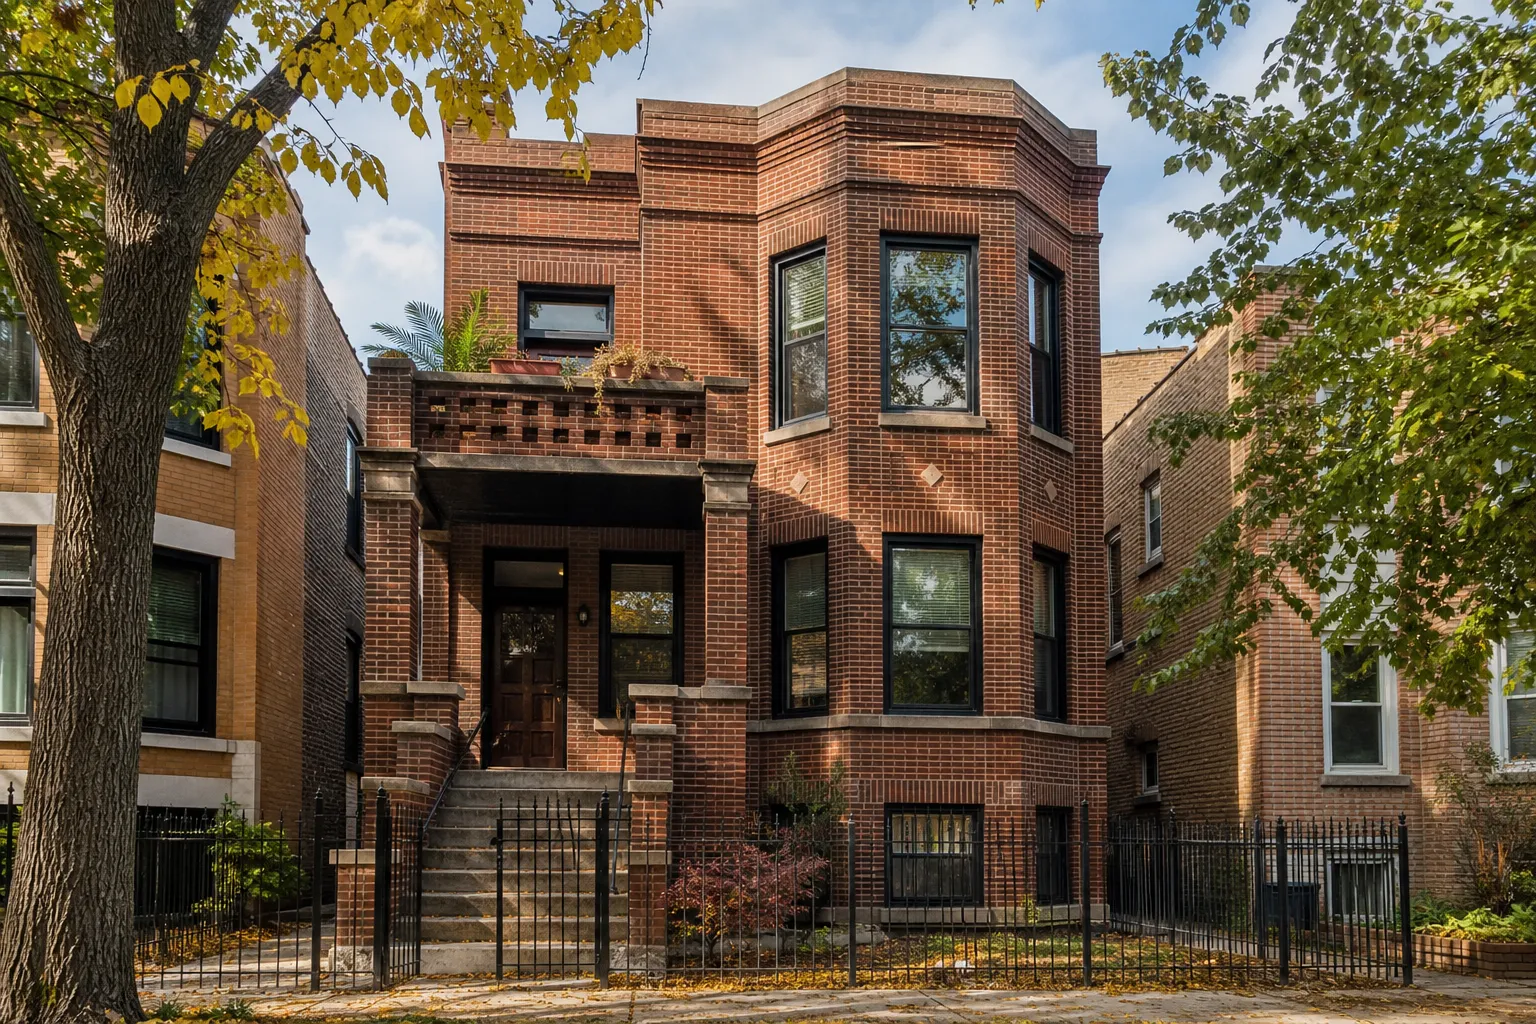
Haughville is Marion County’s highest-yield-on-cost corridor — West Washington Street, Harding Street, and Ladoga Avenue blocks where pre-war double stock trades at $78K–$108K as-is and gross caps can exceed 9% when sponsors budget heavy mechanical rehab and honest vacancy.
Hard money loans in Haughville fund Near Westside BRRRR: acquisition of distressed doubles with deferred maintenance, full-system rehab scopes, and exit to DSCR loans Indianapolis when rent roll clears ratio at 70%–72% LTV.
Haughville geography
Haughville sits west of downtown Indianapolis — bounded by I-70, West Street, and Lafayette Road. The Near Westside corridor differs from Bates-Hendricks and Fountain Square:
- Lowest Marion County basis on double stock — $78K–$108K as-is
- Heaviest rehab scope — $48K–$68K mechanical typical
- Highest block variance — street-by-street diligence non-negotiable
- Eskenazi Hospital and IUPUI employment adjacency — LTR tenant pool
Renters include hospital staff, warehouse workers along Washington Street, and families priced below Near Eastside walkability premiums.
2026 price and rehab bands
| Asset | As-is buy | Rehab | Stabilized ARV |
|---|---|---|---|
| Side-by-side double | $78K–$102K | $48K–$62K | $168K–$198K |
| Up-down double | $82K–$108K | $52K–$68K | $172K–$205K |
| Small MF (3–4 unit) | $95K–$128K | $55K–$75K | $195K–$235K |
Cross-comp Fountain Square or Irvington sales onto Harding Street blocks and appraisers will cut ARV $20K–$30K.
Hard money structure for Haughville
- 8.99%–13.5% interest-only · up to 100% of cost on qualified files, capped at 75% of after-repair value · 7–10 business day close
- Draws tied to inspection milestones — heavy mechanical before cosmetic
- Exit: DSCR Indianapolis at 5.75%–10.5% — plan 70%–72% LTV on tight files
Draw schedule: Harding Street double rehab
| Draw | Milestone | Release | Scope |
|---|---|---|---|
| Draw 1 | Close + 14 days | 20% | Demo, permits, structural assessment |
| Draw 2 | Electrical + plumbing rough | 30% | Knob-and-tube, galvanized replacement |
| Draw 3 | HVAC + roof (if needed) | 30% | Full systems both sides |
| Draw 4 | Finish | 20% | Kitchens, baths, flooring |
A $58,000 rehab on Haughville doubles funds across 100–130 days — model $1,900–$2,400/mo IO on $148K all-in loan.
Worked example: West Washington double BRRRR
Property: Side-by-side on West Washington Street, built 1928, both sides vacant, knob-and-tube, shared boiler.
Acquisition: $86,000.
Rehab: $58,000 — separate HVAC, panels, kitchens/baths, exterior, boiler removal.
Hard money: 87% LTC → $125,280 funded; sponsor cash ~$18,720 + reserves.
Stabilize: $1,175/side ($2,350 gross) — 12-month leases.
Appraisal: $182,000.
DSCR refi at 71% LTV → DSCR ~1.14 — tight but viable on lowest Marion County basis.
NOI math: Vacancy 10%, taxes $265/mo, insurance $165/mo, maintenance $165/mo, PM 8% → NOI ~$1,320/mo vs. debt service ~$1,158/mo at 7.0% on $129K loan.
Worked example: Ladoga Ave — flip vs. hold
Acquisition: $92,000 double — one side tenant at $825/mo. Rehab: $52,000 full mechanical + cosmetic. Flip sale: $175,000 — 8% costs, $9,200 carry → net ~$8,800 spread. Hold alternative: $2,300 gross rent, $178K appraisal → DSCR at 70% LTV extracts ~$22K equity — BRRRR wins.
Haughville vs. Martindale-Brightwood
| Factor | Haughville | Martindale-Brightwood |
|---|---|---|
| As-is basis | $78K–$108K | $88K–$125K |
| Rehab scope | Heavier | Moderate |
| Rent/side | $1,050–$1,275 | $1,150–$1,350 |
| Vacancy model | 9%–10% | 8%–9% |
| Gross cap | 8%–10% | 7%–9% |
| DSCR @ 75% LTV | 1.10–1.18 | 1.15–1.22 |
Haughville rewards highest yield-on-cost; Martindale-Brightwood offers slightly easier DSCR clearance.
Block diligence — non-negotiable
Qualified blocks show:
- Recorded investor or owner-occ sale within 12 months on same block
- No active code enforcement liens
- Comps within 0.5 miles in Haughville — not Bates-Hendricks
- Visible block maintenance — absentee landlord concentration increases vacancy
Avoid: blocks with zero sales in 24 months, industrial adjacency without environmental review, listings with uncurable title defects.
Diligence on Haughville stock
- Galvanized plumbing — full replacement on 50%+ of inventory
- Knob-and-tube — budget $14K–$18K electrical per double
- Foundation — engineer mandatory on pre-1935 stock
- Lead paint — abatement on occupied-side rehab sequencing
- Insurance — $1,600–$2,000/yr on $180K dwelling
- Vacancy — 9%–10% realistic on transitional blocks
When Haughville beats Fountain Square
- Sponsor wants lowest Marion County basis per dollar of rehab
- Highest gross cap tolerance with heavier block diligence
- Experienced BRRRR operator comfortable with 1.12–1.15 DSCR at lower LTV
When you want walkability premium and $1,400+/side rents — Fountain Square spoke.
Haughville BRRRR sequencing
Lowest-basis Marion County doubles require block-first, mechanical-second execution:
- Qualify the block — recorded sale within 12 months, no active code liens, comps within 0.5 miles in Haughville only.
- Acquire at $78K–$108K on Indianapolis hard money — up to 100% of cost on a qualified file, capped at 75% of after-repair value, with a 7–10 business day close.
- Heavy rehab $52K–$68K — galvanized plumbing, knob-and-tube, foundation engineer on pre-1935 stock.
- Stabilize at $1,050–$1,275/side with 9%–10% vacancy modeled honestly.
- DSCR exit at 70%–72% LTV — ratio 1.10–1.18 typical; do not understate opex to force 75% LTV.
Hard money carry at 10.75% IO for 7 months on $145K funded runs ~$9,100 — highest yield-on-cost in Marion County rewards sponsors who survive the diligence and rehab timeline.
Pre-close diligence checklist
- Engineer letter mandatory on pre-1935 foundation when cracks or uneven floors disclosed
- Lead paint abatement plan on occupied-side rehab sequencing
- Insurance at $1,600–$2,000/yr on $180K projected value
- DSCR calculator at 70% LTV before offer — Haughville fails refi when vacancy modeled at 5%
FAQ
First-time sponsor on Haughville?
Possible with experienced GC partner and conservative vacancy — not ideal first Marion County deal.
Three-flat or four-flat in Haughville?
Select small MF inventory exists — confirm property type and DSCR product fit at pre-qual.
Pivot from flip to hold mid-project?
Notify lender before final draws — bridge Indianapolis if lease-up replaces resale.
See Indianapolis metro, Martindale-Brightwood spoke, and Indianapolis BRRRR guide.
Haughville — west-side basis file gates (2026)
Haughville files fail when Fountain Square ARV prices $86K–$92K acquisition doubles, or when tenant-in-place acquisitions skip turnover timeline in carry. Highest Marion County yield bands — highest management intensity.
- Basis: $86K–$92K double acquisitions — $40K–$58K rehab typical
- Rent: $825–$950/side pre-rehab — stabilize before DSCR file
- Panel: Shared service upgrades in draw one — not refi surprise
- Operator: Experienced sponsors with PM capacity — not first-time cosmetic flips
Bridge 8.99%–13.5% IO · Indy rankings · (833) 264-7776.
Underwriting anchor: Acquisition: $86,000. — knob-and-tube, shared boiler on Haughville Indianapolis before IO term.
The voucher ceiling is not the Haughville rent
HUD’s fiscal year 2027 fair market rent for Indianapolis-Carmel is $1,536 for two bedrooms and $1,991 for three bedrooms, effective October 1, 2026, barring a granted reevaluation. Marion County’s 2024 population in that file is 975,809. The tables are HUD’s fair market rent page. The date is in the September 1, 2026 notice (91 FR 56156).
The West Washington example stabilizes at $1,175 a side. That is $361 under the two-bedroom fair market rent. Two sides underwritten at the fair market rent instead of $1,175 would add $722 a month that this block has not signed. Annualized, that fiction is $8,664. Debt-service coverage on Haughville fails when the rent roll is a metro average. Use leases from Harding Street, Ladoga, and West Washington. Do not borrow a Southern Avenue or Fountain Square rent to close the gap.
Why the thin flip does not get rescued by the index
FHFA’s East North Central division, including Indiana, rose 4.5% from July 2025 to July 2026 and 0.1% from June to July 2026. National prices rose 2.6% on the year and 0.3% on the month. The release date is September 29, 2026. Source: FHFA’s monthly house price report.
Illustration: 4.5% of the Ladoga example’s $175,000 sale is about $7,875. That example’s estimated flip net was about $8,800 after costs and carry. One year of division-level appreciation, even if this block matched it, is roughly the entire spread. You should not assume the block matches the division. The hold path in that example, at $2,300 gross and a $178,000 appraisal, is the exit with room. Treat the flip as the weak case unless three Haughville solds say otherwise.
No new doubles are being permitted
Marion County’s building-permit row through August 2026 shows zero units in two-unit buildings and zero units in three- and four-unit buildings. One-unit houses are 744 on the imputed count and 651 reported only. Buildings of five or more contribute 468 units. Census describes the imputed-versus-reported split in the county permit documentation. The year-to-date numbers are in co2608y.txt.
Haughville’s next double is an old double. There is no permitted replacement product in this county file. Apartment units can still compete for a tenant who will accept $1,050 to $1,275 a side. Budget the 9% to 10% vacancy the rest of this guide already uses. A 5% vacancy assumption is how the refinance ratio breaks.
Census Vintage 2025 lists Indianapolis city (balance) at 901,116 residents on July 1, 2025, in the city population folder. That citywide figure does not tell you whether the subject block had a sale in the last year. The block sale is still the gate.
Where the 75% value cap sits on the worked double
Illustration, using the West Washington numbers already on this guide: all-in cost is $86,000 plus $58,000, or $144,000. Eighty-seven percent of cost is $125,280, which matches the funded figure above. Seventy-five percent of the $182,000 appraisal is $136,500. The lower number is $125,280. On this illustration the after-repair cap does not cut the loan. The tight test is income, not leverage. A different appraisal that came in at $160,000 would cap 75% at $120,000, and the 87% cost figure would no longer fund. Run both tests before the offer.
Jaken Finance Group prices the bridge at 8.99%–13.5% interest-only for 6–12 months. A complete file can close in 7–10 business days. Qualified files may reach 100% of cost and are still capped at 75% of after-repair value. Rehab terms while the work is open are summarized on Indiana fix and flip. The permanent loan, after both sides are leased, is DSCR in Indianapolis.
Pack the file in this order:
- A recorded sale on the same block within twelve months.
- No open code lien on the commitment.
- Engineer letter on pre-1935 foundation movement.
- Knob-and-tube and galvanized bids, not allowances.
- Insurance at replacement cost on the post-rehab value.
- Rent comps from Haughville only, with vacancy at 9% or 10%.
Call (833) 264-7776 when a West Washington estate will not wait on a conventional repair list.
Pre-Qualify for Haughville Hard Money · Indianapolis metro · (833) 264-7776