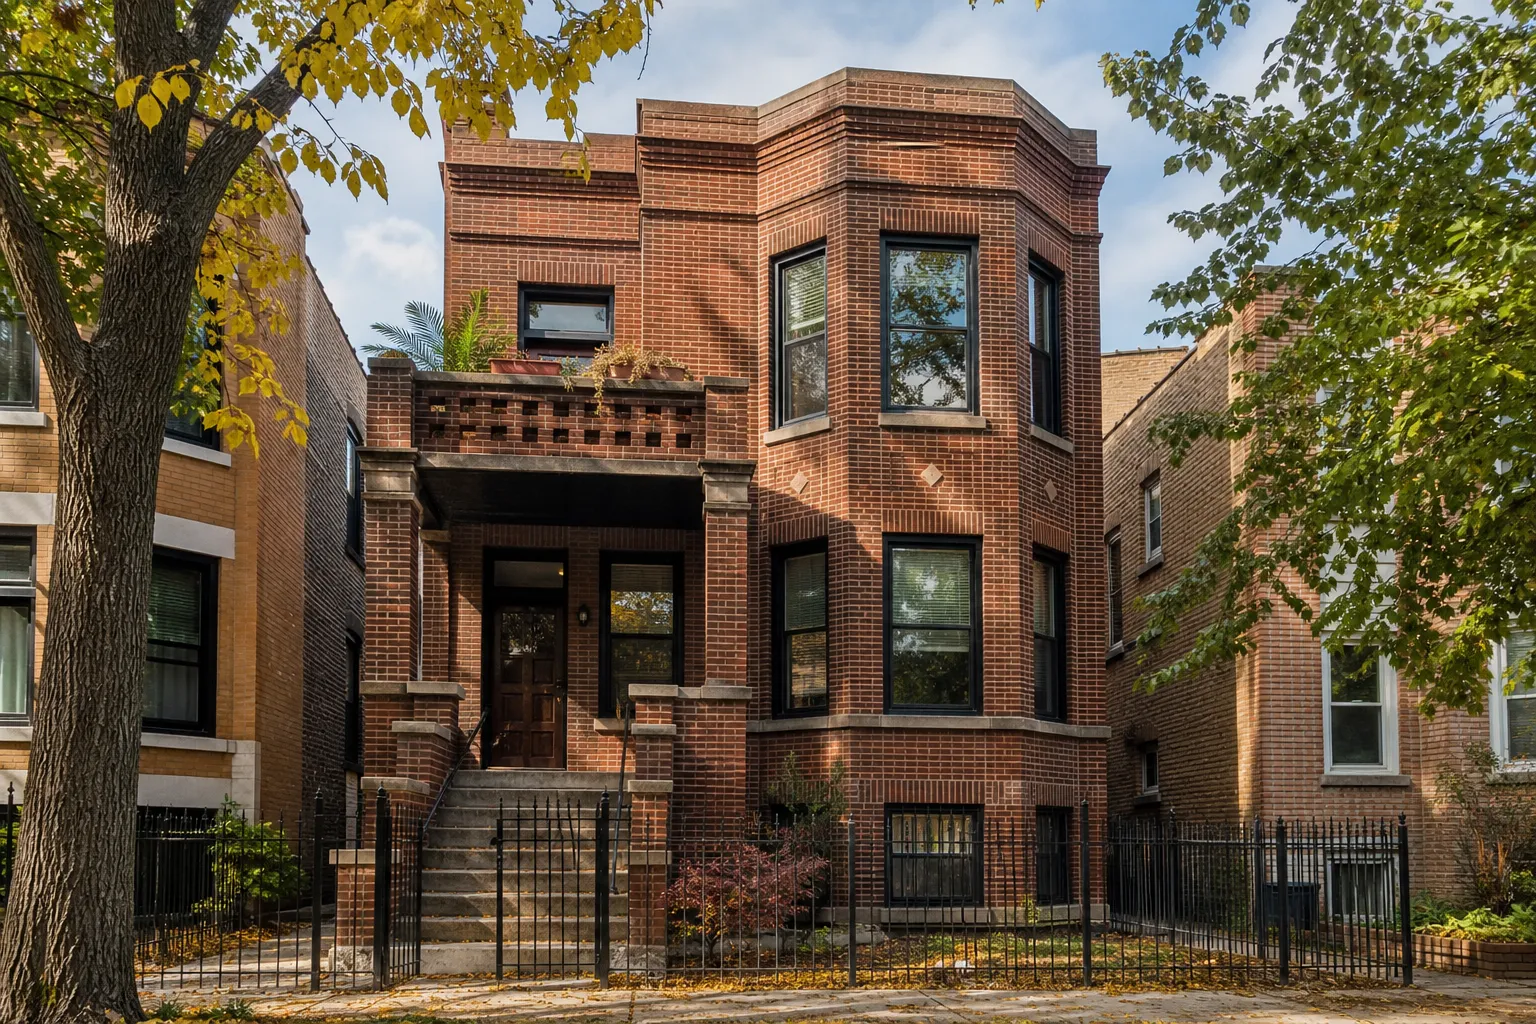
Logan Square is where Chicago BRRRR investors accept higher basis for higher rent ceilings — and DSCR loans in Logan Square are the permanent-debt exit that converts a rehabbed two-flat west of the 606 trail into portfolio equity without W-2 qualification.
This page covers DSCR refi only — acquisition bridge at hard money loans Logan Square · collar comparison at Chicago vs collar BRRRR guide.
Logan Square DSCR thesis — premium rents, premium friction
Logan Square (60647) renovated multifamily commands rents Bridgeport cannot match — but RLTO, DOB compliance, and triennial Cook County reassessment compress NOI if you underwrite like Naperville.
| Asset | 2026 stabilized gross | Typical appraised value | DSCR at 70–75% LTV |
|---|---|---|---|
| Two-flat (interior block) | $3,200–$4,100/mo | $480K–$560K | 1.05–1.20 |
| Two-flat (Milwaukee adjacency) | $3,600–$4,400/mo | $520K–$600K | 1.08–1.22 |
| Three-flat (full gut) | $5,400–$6,800/mo | $680K–$780K | 1.15–1.35 |
Parent hub: DSCR loans Chicago · DSCR Chicago multi-family
No-seasoning refi timeline — Logan Square two-flat
Typical 60–90 day path from last unit leased to DSCR wire:
| Week | Milestone |
|---|---|
| 0 | Both units leased; executed leases uploaded |
| 1–2 | 1007 rent schedule ordered; tax reassessment estimate run |
| 2–3 | Appraisal — comps within 4 blocks, renovated only |
| 3–4 | Underwriting + LLC vesting review |
| 4–6 | Close at 70–75% LTV; hard money retired |
Seasoning trap: Banks wait 6–12 months on purchase price. No-seasoning DSCR underwrites as-repaired appraised value — the recycle engine for Logan Square portfolio builders.
Jaken Finance Group Logan Square DSCR parameters (2026)
- Rates: 5.75%–10.5% · Leverage: up to 80% LTV cash-out; up to 85% on purchase or rate-and-term in select markets for qualified borrowers
- DSCR minimum: 1.0+; 1.15+ for best pricing
- Entity: LLC standard · Timeline: 7–14 business days with clean file
Model with DSCR calculator.
Worked example: Fullerton side-street two-flat DSCR exit
Note: This is a DSCR refi file only — acquisition bridge math lives on the Logan Square hard money page (different property profile: Kedzie three-flat).
Property: Brick two-flat on Fullerton side street west of 606 trail — both units vacant post-rehab, CO cleared month 7.
Stabilized rents: $2,050/mo (3BR upper) + $1,800/mo (2BR lower) = $3,850/mo gross Appraised value at refi: $518,000 — comps restricted to 60647 renovated two-flats, not Lincoln Park Property tax (stress-tested): $985/mo post-reassessment (+14% vs seller bill) Modeled opex: 31% (RLTO compliance, insurance, 6% vacancy, management) DSCR refi at 73% LTV: $378,140 @ 8.45% DSCR ratio: 1.12 — clears refi; sponsor recycled ~$72K for Avondale acquisition
Why 73% LTV and not higher: when tax reassessment lags the appraisal, the stressed tax line usually caps proceeds before the leverage limit does — we stress tax at post-close assessed value before term sheet.
Cook County tax line — most common refi miss
Appraisers support $518K value; tax bill still shows the pre-rehab assessed value until the next reassessment catches up. Underwriters model tax at post-renovation assessment — if you use seller’s $720/mo tax in pro forma but underwriter uses $985/mo, DSCR drops 0.06–0.10. Pull Cook County assessor data before submitting refi intent.
Timing matters too. The Assessor’s 2026 calendar confirms that City of Chicago parcels are not in this year’s general reassessment. The City’s next turn in the three-year rotation is 2027. Permit work, property divisions, and similar changes can still trigger an individual reassessment sooner. A two-flat rehabbed under permit in 2026 may see the new value before the citywide cycle arrives. Stress the tax line on both paths when you plan a 2026 or 2027 cash-out.
RLTO and lease file requirements
- Security deposit held apart from your own funds in a federally insured, interest-bearing account at an Illinois bank, with a receipt to the tenant
- Heat obligations if landlord-paid — model $1,400–$2,800/unit/winter in opex
- Executed leases matching 1007 market rent — not prior tenant’s below-market rollover
See Chicago RLTO compliance guide.
Milwaukee Avenue vs interior block — refi math split
Logan Square DSCR files fail when sponsors comp Milwaukee frontage rent onto interior block appraisals — or vice versa. Underwriters size permanent debt to the subject block, not corridor medians.
| Block type | Typical refi appraisal | Achievable gross | Common LTV cap | Ratio band |
|---|---|---|---|---|
| Interior (Fullerton/Kedzie side streets) | $480K–$540K | $3,200–$3,900/mo | 73–75% | 1.08–1.18 |
| Milwaukee adjacency (≤1 block) | $520K–$600K | $3,600–$4,400/mo | 70–73% | 1.06–1.15 |
| Three-flat (Kedzie corridor) | $680K–$780K | $5,400–$6,800/mo | 70–72% | 1.12–1.28 |
606 trail spillover: Blocks within 400 feet of the trail command $150–$250/mo premium per unit on renovated two-flats — but also attract higher acquisition basis. Model both in the DSCR exit before you offer on a trail-adjacent file.
Inherited RLTO tenant — turnover refi scenario
When one unit inherits a below-market RLTO tenant at acquisition, permanent debt timing splits into two paths:
Path A — hold both units, refi on in-place rent: Underwriter uses actual leases, not 1007 market rent. A $1,350/mo RLTO upper plus $1,800/mo market lower on a $485K appraisal often clears only 68–70% LTV — not the 75% modeled on full market rents. Budget $180/mo RLTO compliance in opex.
Path B — turnover upper, then refi: RLTO notice, turnover, and re-lease add 60–120 days but unlock 1007 market rent on both units. A $518K appraisal with $3,850/mo gross (Path B) vs $3,150/mo (Path A) is the difference between 73% LTV clearing and a failed refi file.
See the illustrative Bridgeport BRRRR scenario for an illustrative payment and bridge-payoff test. Its rent and expense assumptions are not evidence of a completed refinance, tenancy status, or local ordinance treatment.
Logan Square by the numbers — a deep two-flat comp pool
ZIP code 60647 covers Logan Square plus parts of Bucktown and nearby blocks, so treat its medians as a backdrop rather than a comp. Per the Census Bureau’s 2020–2024 American Community Survey, summarized by Census Reporter:
- Median gross rent: $1,774/mo
- Renter-occupied homes: 61.2%
- Median owner-occupied value: $586,200
- Units in two-unit buildings: 7,138; in three- and four-unit buildings: 11,672 — together about 44% of the ZIP’s 42,740 housing units
For comparison, two- to four-unit buildings hold roughly 26% of housing units citywide in the 2024 one-year ACS, per Census Reporter’s Chicago profile. Logan Square has close to twice the citywide share.
That density is good news for refinance appraisals. Unlike neighborhoods dominated by high-rises, an appraiser here can usually find renovated two-flat sales within a few blocks. The risk is the opposite: Bucktown sales sit in the same ZIP and can inflate a pro forma. Your appraiser will reject them if the block, finish level, or lot size does not match.
Prices are still moving. The FHFA all-transactions house price index for the Chicago-Naperville-Evanston metro division rose about 6.2% from Q2 2025 to Q2 2026, per FRED series ATNHPIUS16984Q. Metro-wide gains do not guarantee your block’s value. Order the appraisal on the subject’s own sales evidence.
Voucher ceilings: 60647 vs. Avondale (FY2026)
HUD sets Small Area Fair Market Rents by ZIP code across the Chicago-Joliet-Naperville HUD Metro FMR Area. From HUD’s FY2026 FMR documentation:
| ZIP | 2-bedroom FMR | 3-bedroom FMR |
|---|---|---|
| 60647 (Logan Square) | $2,220 | $2,860 |
| 60618 (Avondale / Irving Park) | $1,990 | $2,560 |
These are gross figures that include tenant-paid utilities. Even so, a 3BR voucher unit in 60647 has a higher ceiling than the $2,050 market upper in the worked example above. Sponsors weighing a move north into Avondale should price the roughly $300 lower 3BR ceiling into the hold.
Fair Notice timing on inherited tenants
The turnover plan in Path B above depends on notice periods set by Chicago’s 2020 Fair Notice amendments. Per the City of Chicago RLTO summary, a landlord must give a tenant who is not in eviction:
| Tenant’s time in unit | Notice to end month-to-month, not renew, or raise rent |
|---|---|
| Under 6 months | 30 days |
| 6 months to 3 years | 60 days |
| More than 3 years | 120 days |
These notice rules apply to all residential units, even ones the RLTO otherwise exempts. A long-tenured upper tenant means a four-month runway before you can reset rent. Build that into the hard money term, or the bridge may mature before the 1007 market rent is achievable.
Two other RLTO rules affect Logan Square cash flow. Late fees are capped at $10 a month on the first $500 of rent plus 5% of the amount above $500. On the example’s $2,050 upper, the maximum late fee is $87.50. Tenants also get a one-time right to stop a nonpayment eviction by paying all back rent and the landlord’s court filing fees. Model collections with both limits in mind.
Transfer taxes on the acquisition leg
Closing costs on the purchase reduce the equity you can later pull out. The City of Chicago transfer tax page sets the total at $5.25 per $500 of price. Generally the buyer pays the $3.75 city portion and the seller pays the $1.50 CTA portion. Illinois adds a state tax of 50 cents per $500 under 35 ILCS 200/31-10.
Example: on a $525,000 Logan Square two-flat, the buyer’s city portion is $3,937.50. The CTA portion is $1,575 and the state tax is $525. Who pays the state share is a contract point.
The refinance itself is different. These taxes apply to transfers of title or beneficial interest, so a DSCR refi that leaves title unchanged does not trigger them. Watch entity changes, though. The state tax also reaches transfers of a controlling interest in an entity that owns Illinois real estate. Restructuring your LLC right before the refi can create a taxable event, so ask your attorney first.
Logan Square DSCR risks
606 trail gentrification premium — rent supports ratio; basis on Milwaukee-adjacent blocks leaves thin cushion. Over-improvement — comp within four blocks. RLTO turnover on inherited tenants delays stabilization.
Underwriting checklist
- Executed leases + 1007
- CO all units · LLC docs · Insurance quote
- Tax stress +15% · Hard money payoff
- Scope summary if no-seasoning file
Related
- Hard money loans Logan Square
- illustrative Bridgeport BRRRR scenario — lower-basis comparison
- Chicago BRRRR strategy
Logan Square DSCR — two-flat refi gates (2026)
Logan Square files fail when Wicker Park comps price Milwaukee corridor rent, or refi starts before RLTO turnover completes on inherited tenants.
- Worked refi: $3,850/mo gross ($2,050 + $1,800) → 73% LTV at 8.45%
- Seasoning: Select no-seasoning with appraisal + executed leases
- Appreciation lane: Thinner yield — model hold vs collar RLTO-free exit
- Bridge: Acquisition on Logan Square hard money
Underwriting anchor: Stabilized rents: $2,050/mo (3BR upper) + $1,800/mo (2BR lower) = $3,850/mo gross — refresh executed lease, insurance quote, and tax reassessment before DSCR application. DSCR 5.75%–10.5% · Chicago hub · (833) 264-7776.
Stabilized a Logan Square two- or three-flat? Pre-qualify for DSCR refi or call (833) 264-7776.