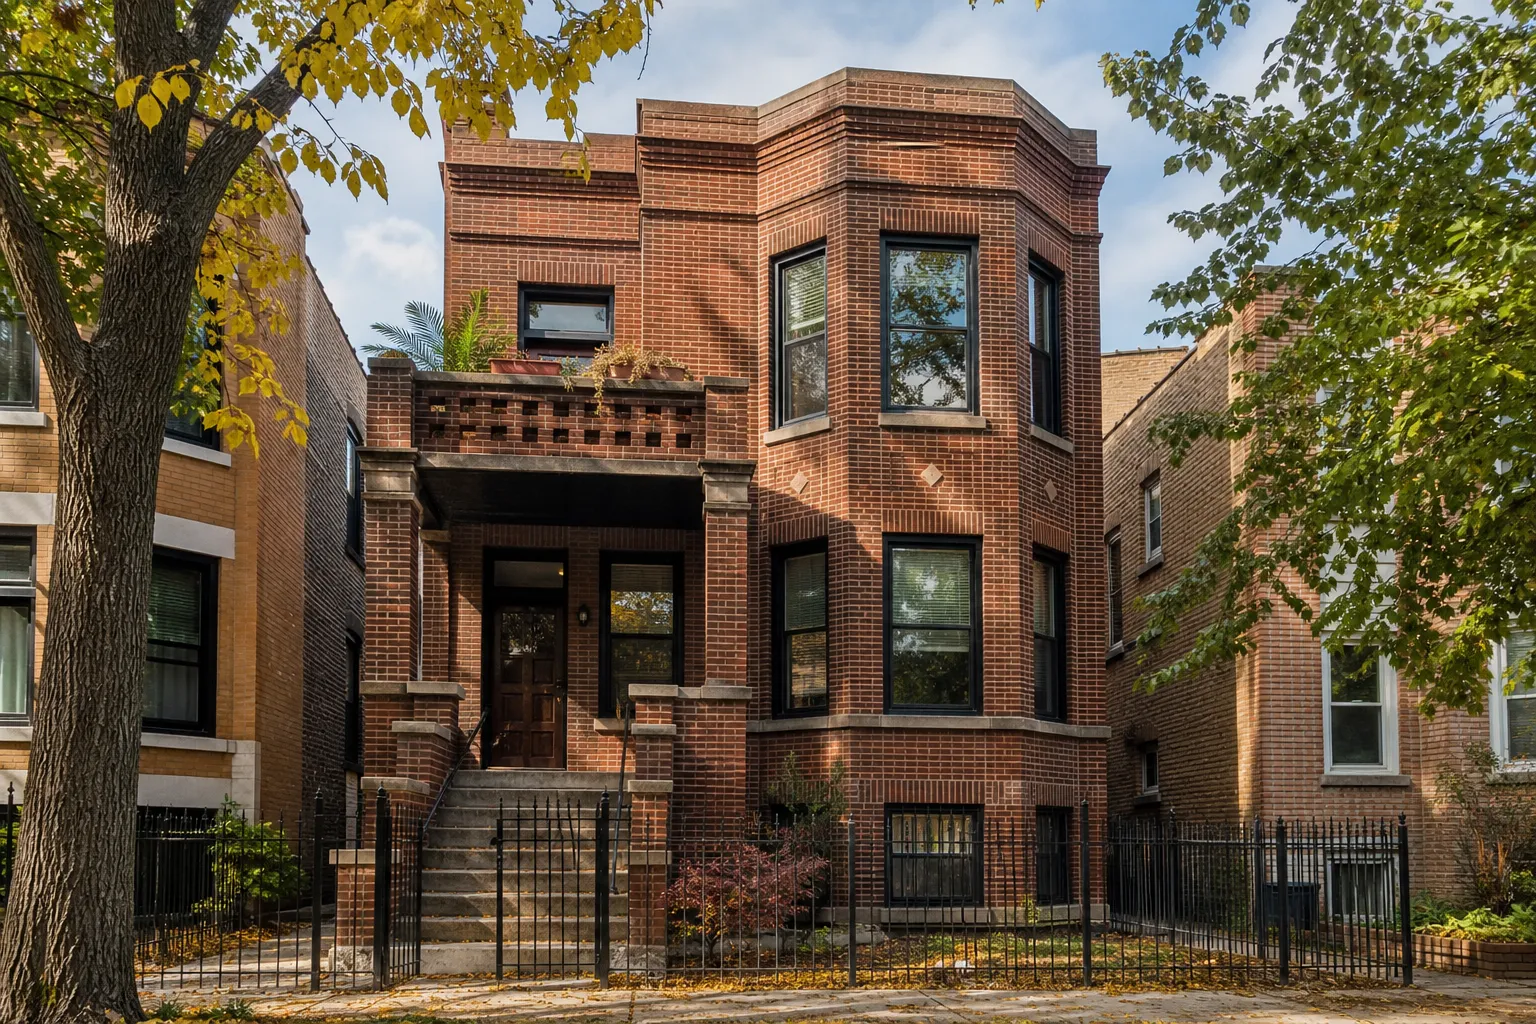
Belmont Cragin is one of the Northwest Side’s most active and affordable investor markets — a dense, working-family community of brick two-flats, bungalows, and single-family homes stretching across the 60639 and 60634 zip codes. Heavily Latinx and deeply rooted, the neighborhood combines a lower acquisition basis than the North Side with fast turnover and strong rental demand. Hard money loans in Belmont Cragin serve investors who need to close quickly in a market where good properties do not sit.
The defining feature of Belmont Cragin in 2026 is velocity. Listed pricing has run near $392K with average sale prices climbing sharply year over year, and homes have been moving in roughly 20 days — single-family stock even faster. That pace punishes slow capital. An investor relying on a 45-day bank approval loses to the one who can show proof of funds and close in a week.
The Belmont Cragin investor profile
The sponsor mix here reflects the neighborhood’s affordability and rental depth:
- BRRRR operators chasing a low all-in basis and reliable rents, refinancing into long-term holds.
- Two-flat value-add landlords updating dated masonry buildings for a rooted, credit-worthy renter base.
- Neighborhood-rooted, often Spanish-speaking investors buying their second or third building on familiar blocks.
- Appreciation-aware flippers capturing the neighborhood’s strong year-over-year price movement with disciplined, resale-ready rehabs.
The through-line is speed plus basis discipline. Belmont Cragin is not a luxury-finish market; it rewards clean, durable rehabs delivered quickly into demand that is already there.
What Belmont Cragin properties look like in 2026
Inventory skews toward brick two-flats, Chicago bungalows, and modest single-family homes, many built mid-century and carrying deferred mechanicals. The affordability relative to the rest of the Northwest Side is the whole thesis — it is where the spread lives.
| Property type | 2026 buy range | Typical rehab | Notes |
|---|---|---|---|
| Single-family / bungalow | $330K–$410K | $45K–$100K | Fastest resale; owner-occupant demand |
| Two-flat | $370K–$470K | $60K–$130K | Core BRRRR and dual-unit rental target |
| Small mixed-use (Fullerton / Grand corridors) | $420K–$560K | $90K–$170K | Storefront + units; verify zoning |
Rehab costs track citywide Chicago norms — roughly $75K–$150K for a full two-flat gut including electrical, plumbing, kitchens, baths, and masonry. Because basis is lower here than in Avondale or Logan Square, the same rehab dollar produces a healthier margin, which is why the neighborhood works for both flips and BRRRR holds.
Financing Belmont Cragin deals with hard money
Banks stall on non-owner-occupant buyers proposing meaningful rehab, and in a 20-day market that delay is fatal. Chicago hard money lenders underwrite the deal — purchase, ARV, rent comps, and exit — and close on the timeline the market demands.
Jaken Finance Group offers Belmont Cragin investors:
- Up to 100% of cost on qualified files, always cut to 75% of after-repair value if that number is lower
- Rehab draws inside that cap, released on milestones, not as a blank check for every line item
- Interest-only fix-and-flip terms of 6–12 months at 8.99%–13.5%. A longer hold can use a bridge at the same rate band for 12–24 months
- 7–10 business day closes when the file is complete — often the deciding factor in this fast-moving market
Flip exits route through fix and flip loans in Chicago; hold exits pivot to DSCR loans in Chicago once units are leased. Compare current metro rates and prices in the Illinois hard money and Chicagoland rate report.
Worked example: a two-flat BRRRR near Fullerton
An investor targeting the neighborhood’s rental depth acquired a $385,000 brick two-flat off Fullerton — one unit vacant, one occupied on a month-to-month lease, both dated.
Rehab budget: $96,000 — electrical, two full kitchens and baths, refinished floors, new furnace and water heaters, tuckpointing All-in cost: $481,000 Hard money structure: 88% LTC — $338,800 acquisition funding plus a $96,000 rehab holdback Stabilized rents: roughly $1,900–$2,100 per unit after rehab, supporting the refinance Exit: No-seasoning DSCR cash-out at 70–75% LTV once both units leased Net outcome: Capital recycled in under nine months with a stabilized hold in a low-vacancy submarket
The deal worked because the sponsor moved fast on acquisition, priced the rehab to the block, and underwrote to current leased comps — not to the neighborhood’s eye-catching year-over-year appreciation headline.
Belmont Cragin-specific diligence
In a fast market, discipline matters more, not less. Pull a 311 violations search and confirm status before waiving inspection — dense two-flat stock here often carries unpermitted work. Verify legal unit counts against Cook County Assessor records; illegal conversions are a recurring issue on the Northwest Side and will not appraise or refinance cleanly. Underwrite rents to current leased comps, and factor RLTO notice and relocation for occupied units. Because properties move quickly, have financing, entity docs, and a contractor ready before you offer — the winning bid here is usually the one that can actually close.
Frequently asked questions
Why is Belmont Cragin attractive for BRRRR in 2026?
Two reasons: basis and velocity. Median list pricing sits near $392K — well below North Side comps — while homes have been moving in roughly 20 days and prices have climbed sharply year over year. A lower all-in cost plus strong rental demand from a rooted, working-family renter base makes the hard-money-to-DSCR path pencil where a thin flip might not.
How fast do I need to move on a Belmont Cragin deal?
Fast. With median days on market around 20 and single-family homes moving even quicker, hard money’s 7–10 day close is often the difference between winning and losing. Have your proof of funds, entity docs, and contractor lined up before you write the offer.
Can hard money finance a Belmont Cragin two-flat with an occupied unit?
Yes, with proper RLTO notice and a rehab plan that sequences around the tenant. Budget relocation and timeline as borrower costs, and clear any open violations before the DSCR refinance or resale.
What the two ZIPs priced through August 2026
Belmont Cragin covers 60639 and 60634. Treat them as neighbors, not as one price.
The Zillow Home Value Index for 60639, mid-tier single-family and condo, smoothed and seasonally adjusted, was $335,197 on August 31, 2026. It was $319,424 a year earlier, a gain of about 4.9%. The smoothed rent index was about $1,776, up from about $1,642, or about 8.1%. In 60634 the value index was $380,567, up from $358,724, about 6.1%. Rent there was about $1,825, up from about $1,721, about 6.0%. The series are on Zillow Research.
Rent in 60639 rose faster than values. That is the pattern a hold wants, if the lease on your two-flat matches real units and not the ZIP blend. Values in 60634 rose about as fast as rents, and the typical value sits roughly $45,000 higher. Do not average the ZIPs into one after-repair value. A Fullerton two-flat and a 60634 bungalow need separate comps.
These indexes are modeled typical values. They are not the list price of the house you are buying, and they are not your appraisal. A renovated resale can clear more than $335,000 in 60639. A tired brick two-flat can trade for less. Pull the parcel on the Cook County Assessor before you lock the basis.
Chicago prices, jobs, and building permits
The S&P CoreLogic Case-Shiller Chicago home price index, not seasonally adjusted, was 238.61 in July 2026. It was 223.30 in July 2025. That is a gain of about 6.9% (CHXRNSA). The metro index outran 60639’s 4.9% value gain. Do not paste the Case-Shiller move onto a Belmont Cragin block that has not printed new solds.
Unemployment in the Chicago-Naperville-Elgin metro was 4.9% in August 2026, up from 4.4% in August 2025 (CHIC917UR). Prices rose while the jobless rate rose. Do not tell the story as “jobs are tight, so any rehab leases.” Underwrite the tenant with current leases on the same street.
The metro authorized 2,100 new private housing units in August 2026, versus 1,473 in August 2025 (CHIC917BPPRIV). That is about 43% more permits. New supply is a metro fact. Your two-flat still competes with other brick buildings on the Northwest Side, not with a downtown tower. It does mean finished housing is still being approved. Price the exit to leased comps, not to a shortage slogan.
The average 30-year fixed mortgage was 7.28% in the week of October 1, 2026 (MORTGAGE30US). That is the benchmark an owner-occupant sees. It is not the coupon on this bridge. Jaken Finance Group prices fix-and-flip and bridge interest-only loans from 8.99% to 13.5%. The gap versus 7.28% is what you pay to close in 7–10 business days on a property a bank will not fund as-is. Statewide notes are on Illinois fix-and-flip loans and Illinois DSCR loans.
A cap check on a $460,000 two-flat
Illustration, separate from the Fullerton example above. Purchase $370,000. Rehab $90,000. All-in $460,000. Stabilized value used for the cap test: $540,000.
One hundred percent of cost is $460,000. Seventy-five percent of $540,000 is $405,000. The loan funds the lower number, so the maximum here is $405,000. Cash still in the deal is $55,000, before points and prepaid interest.
At 11.25%, which sits inside 8.99%–13.5%, monthly interest on $405,000 is $3,797. Nine months of interest, inside a 6–12 month fix-and-flip term, is $34,173. If lease-up slips past month nine, switch the model to a bridge term of 12–24 months in the same rate band instead of hoping the note extends itself.
A later cash-out can go up to 80% of value for a qualified borrower. Eighty percent of $540,000 is $432,000. That retires the $405,000 bridge and leaves about $27,000 before refinance costs. It does not cash you out of the $55,000 you posted unless the appraisal comes in higher. Purchase DSCR leverage can reach 85%, and rate-and-term can reach 85%, in select markets. Rates on those loans run 5.75%–10.5%. The refinance still needs both units leased. See how LTV and LTC differ and the DSCR cash-out path.
There is no minimum FICO on select Jaken Finance Group programs. The two-flat, the scope, and the exit still have to carry the file. The property must be non-owner-occupied.
Permits, lead paint, and an occupied unit
Confirm the permit path with the Chicago Department of Buildings before demo. Do not guess a dollar threshold from another neighborhood. Open violations and an illegal third unit will not appraise cleanly, which is why the assessor check matters before you waive inspection.
Most Belmont Cragin brick was built before 1978. The EPA banned lead paint sales for homes that year and still finds lead paint in a large share of older houses. If the exit is a rental and the work disturbs paint, use a firm certified under the lead renovation rule. Put that firm in draw one, not in the punch list.
An occupied unit needs a rehab sequence the tenant can live through, or a relocation cost you pay. Follow the city’s landlord-tenant notice rules for that unit. Budget the lost rent as a borrower cost. Do not hide it inside the after-repair value.
Papers that win a 60639 contract
- Parcel print from the Cook County Assessor showing the legal unit count.
- A 311 violation search with each open item assigned to a draw.
- Three sold two-flats or bungalows in the same ZIP, not a North Side average.
- Rent comps from current leases, split by 60639 versus 60634.
- A scope that prices electrical, plumbing, masonry, and lead-safe work on separate lines.
- The $405,000-style cap test for your own value, plus nine months of interest in cash.
- Entity documents and a landlord policy quote for as-is and finished replacement cost.
Call (833) 264-7776 with the Fullerton or Grand address before the seller’s attorney writes a financing rider. If you would rather start from the loan type, use the loan-fit form. The document list that applies beyond this neighborhood is in fix-and-flip requirements.